If your business puts vehicles on the road, commercial auto insurance covers the cars, trucks, and drivers your personal policy leaves out. It pays for the injuries and property damage a work-related accident can cause, whether your crew drives a company truck, a service van, or their own car on the job. This guide breaks down how coverage works for Indiana and tri-state businesses, and how to tell which type you actually need.
Key Takeaways
- Commercial auto insurance covers the vehicles your business owns, leases, rents, or uses for work, and it responds in situations where a personal auto policy won’t.
- Personal auto policies commonly exclude business use. If an employee drives their own car for work, their personal policy is primary, and your business’s non-owned coverage only sits above it.
- Hired and non-owned auto (HNO) is one endorsement covering rented or borrowed vehicles (hired) and employees’ personal vehicles used for work (non-owned). It’s liability-only and doesn’t cover damage to the vehicle or the driver’s own injuries.
- Indiana requires 25/50/25 minimum liability on any vehicle operated on public roads, and you must keep that financial responsibility in effect the entire time the vehicle is on the road.
- Commercial auto premiums have been rising industry-wide as vehicles get more expensive to repair and as distracted driving and litigation add pressure.
- As an independent agency, Torian Insurance shops multiple carriers to match your commercial auto and HNO coverage to how your business actually uses vehicles.
What Is Commercial Auto Insurance, and Who Needs It?
Commercial auto insurance is coverage for vehicles your business owns, leases, rents, or uses for work. It pays for bodily injury and property damage from an accident involving a covered vehicle, and it can add protection for theft, vandalism, and weather. In most cases, if you drive for work, you need it.
Commercial auto is one piece of a broader business insurance program, and you likely need it if your work depends on vehicles. Around Evansville and the tri-state, that includes:
- Contractors and tradespeople with work trucks and equipment trailers
- Landscapers and lawn crews hauling mowers and materials
- Plumbers, electricians, and HVAC techs running service vans
- Delivery, courier, and freight operations
- Retailers and shops that make deliveries or run errands
- Sole proprietors who rely on a single work vehicle
Even if you work alone, a personal policy usually won’t cover a vehicle used mainly for the business, so a commercial policy is worth a look. Trades often have to prove they carry commercial auto before a general contractor or property manager will let them on a job, usually by handing over a certificate of insurance. Our contractor insurance overview covers what is typically required.
Which Auto Coverage Applies to Your Situation?
The right coverage depends on who owns the vehicle and how it’s used. This quick guide maps four common tri-state situations to the coverage that responds first.
| Vehicle and how it’s used | Whose policy responds first | Coverage to look for |
|---|---|---|
| A vehicle your business owns or leases, driven for work | The business’s commercial auto policy | Commercial auto (Business Auto Coverage Form) |
| An employee’s personal car used for a work errand or client visit | Employee’s personal auto is primary; your business’s non-owned coverage sits above it | Non-owned auto (part of the HNO endorsement) |
| A truck or van your business rents or borrows for a job | The rental or owner terms and your hired auto coverage | Hired auto (part of the HNO endorsement) |
| An owner or executive who drives a company car, has no personal policy, and borrows or rents a car for personal use | The company policy, via the DOC endorsement | Drive Other Car (DOC) endorsement |
In plain terms, hired and non-owned auto (HNO) is a single endorsement that combines two coverages: hired auto for vehicles you rent or borrow, and non-owned auto for employees’ personal vehicles used for work. The sections below explain each row and where the gaps hide.
How Is Commercial Auto Insurance Different From Personal Auto Insurance?
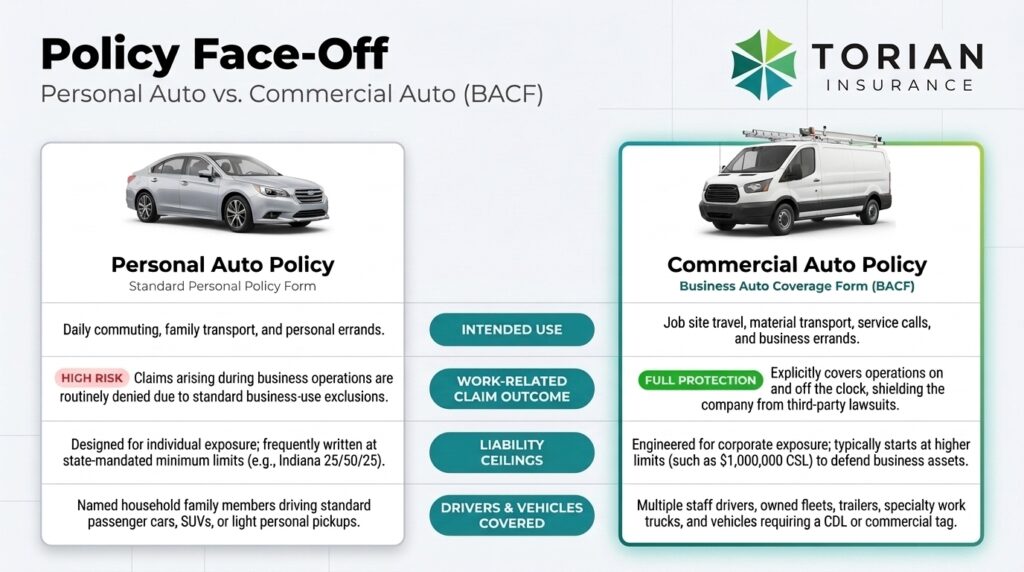
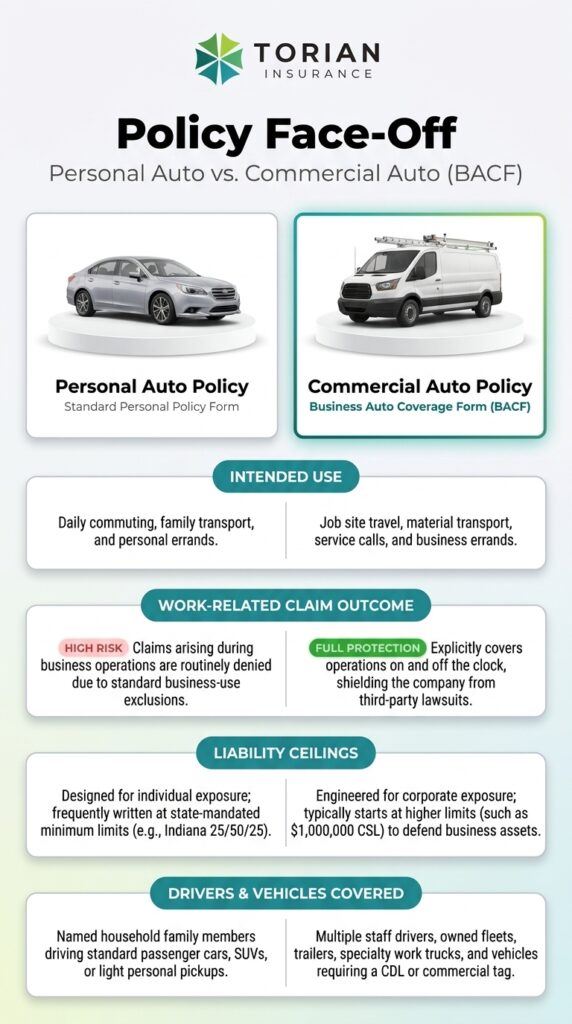
The core difference is business use. Personal auto policies are written for personal driving and commonly exclude business use, so a claim from a work-related accident can be denied. Commercial auto is built for work vehicles, business liability, and multiple drivers.
Commercial auto is written on the Business Auto Coverage Form (BACF), the standard policy form insurers use for business vehicles. Here’s how the two policies compare in practice:
- Purpose and use. Personal auto is for commuting and errands. Commercial auto is for work vehicles, business errands, and vehicles driven by more than one employee.
- The business-use exclusion. A personal insurer can deny a work-related claim because the vehicle was being used for business, which is a common exclusion in personal policies.
- Liability limits. Personal policies often carry the state-minimum limits, while commercial policies usually carry much higher limits, because a business faces larger claims and lawsuits.
- What and who is covered. Commercial auto can cover several vehicles and drivers at once, larger vehicles that need a CDL or a commercial tag, and use both on and off the clock.
For a business owner who occasionally uses a personal vehicle for light work, a personal policy may be enough. Once a vehicle is used regularly for the business, a commercial policy is the reliable fit.
Do I Need Commercial Auto if Employees Drive Their Own Cars? Hired and Non-Owned Auto Explained
Yes. If employees drive their own or rented vehicles for work, hired and non-owned auto (HNO) coverage fills a gap your commercial and personal policies leave open. When an employee runs a work errand in their own car, their personal auto policy is primary, and your business’s non-owned coverage only responds above it.
Non-owned coverage steps in when the employee’s personal policy limits fall short, or when the personal insurer denies the claim because the car was used for business. The industry guidance is blunt on this point: “The employee’s personal auto policy is always the primary source of coverage.”
HNO bundles two situations into one endorsement:
- Hired auto covers vehicles your business rents, leases, or borrows for work. (For personal rentals, our guide on rental car insurance coverage covers how that works.)
- Non-owned auto covers employees’ personal vehicles when they’re used for business. The most common scenarios are routine errands, like an employee driving to the post office to drop off or pick up mail or to the bank to make a deposit, along with supply pickups and client visits.
One thing to watch: HNO is liability-only. It protects the business from a third-party lawsuit, but it doesn’t pay for damage to the employee’s car or for the employee’s own injuries. If an employee is hurt in a work-related crash, those injuries are primarily covered by workers’ compensation, which is the employee’s exclusive remedy for on-the-job injuries. Auto insurance can still play a secondary role, such as the at-fault driver’s liability or uninsured motorist coverage, but for the employee’s own injuries workers’ compensation usually responds first. That’s why workers’ compensation and commercial auto coverage often work together for businesses with employees on the road.
There’s also a related endorsement for owners and executives. Drive Other Car (DOC) coverage is a separate endorsement for someone who drives a company car and has no personal auto policy of their own. It extends protection when that person borrows or rents a car for personal use.
Is Commercial Auto Insurance Required in Indiana?
Yes. Indiana requires liability coverage on any motor vehicle operated on public roads, including business vehicles. Under Indiana Code 9-25-4-5, the state sets minimum liability limits, and financial responsibility must stay in effect the entire time the vehicle is on the road.
Indiana’s minimum is written as 25/50/25:
- $25,000 for bodily injury to or the death of one person
- $50,000 for bodily injury to or the death of two or more people in one accident
- $25,000 for damage to property in one accident
Those are minimums, not recommendations. Most businesses carry much higher limits, because a single serious accident can exceed the state minimum quickly. Commercial auto is also one of the coverages tied to Indiana’s small business insurance requirements, alongside workers’ compensation for businesses with employees.
As an independent agency based in Evansville and licensed across the tri-state (Indiana, Kentucky, and Illinois), Torian Insurance helps businesses meet these requirements and set limits that fit their risk. Requirements vary by state, so confirm the rules wherever your vehicles operate.
What Does Commercial Auto Insurance Cover?
A standard commercial auto policy covers liability for the injuries and property damage you cause, plus physical damage to your covered vehicles through collision and comprehensive. Most policies also include uninsured and underinsured motorist coverage.
The core pieces of a policy are:
- Liability. Pays for others’ injuries and property damage when your driver is at fault.
- Collision. Pays to repair or replace your vehicle after a crash.
- Comprehensive. Covers theft, vandalism, fire, flood, and other non-collision damage.
- Uninsured and underinsured motorist. Covers you when the at-fault driver has no coverage or too little.
Many businesses add endorsements to match their work, such as hired and non-owned auto, on-hook towing, trailer interchange, motor truck cargo, rental reimbursement with downtime, and roadside assistance. Which ones make sense depends on the vehicles you run and the risks you face.
How Much Does Commercial Auto Insurance Cost, and How Can You Lower It?
There’s no flat rate. Commercial auto premiums depend on your vehicles, how you use them, your drivers’ records, your location, and the limits you choose. Industry-wide, commercial auto costs have been rising.
The main factors carriers look at are:
- The type, weight, and value of your vehicles
- How many vehicles and drivers are on the policy
- How the vehicles are used and what they haul
- Driving records and claims history
- Where the vehicles are based and garaged
- The coverage limits and deductibles you select
On the market as a whole, commercial auto costs have been climbing as vehicles become more expensive to repair (new materials, sensors, and computer systems) and as distracted driving and litigation trends add pressure. That makes it worth reviewing your policy regularly rather than setting it and forgetting it.
A few practical ways to keep premiums in check:
- Vet the driving records of anyone who will operate a company vehicle
- Add safety and anti-theft technology, such as dash cameras and collision warning
- Bundle policies where it makes sense, for example pairing commercial auto with commercial property insurance or workers’ compensation
- Ask your agent which discounts you qualify for, and revisit limits as the business changes
How to Get the Right Commercial Auto Coverage
Start by mapping how your business uses vehicles, then match coverage to each situation. The simplest way to do that is to work with an independent agent who can shop multiple carriers and compare options for you. Commercial auto is usually its own policy, with your specific vehicles scheduled, or listed, on it, though it’s often packaged alongside other business coverage such as a business owner’s policy (BOP).
A quick way to prepare:
- Inventory your vehicles and how each one is used
- List every employee who drives for the business
- Decide whether you need HNO for employees’ own or rented vehicles
- Set liability limits that fit your exposure, not just the state minimum
- Plan to review the policy whenever you add vehicles, drivers, or locations
Your personal auto carrier may also offer business policies, but shopping around usually gets a better fit for the price.
How Torian Insurance Helps
As an independent agency, we work for you, not a single carrier. That means we can shop multiple carriers and match your commercial auto and hired and non-owned coverage to how your business actually uses vehicles, instead of fitting you into one company’s template.
Torian Insurance is Evansville’s largest locally owned independent insurance agency, serving Southern Indiana and the tri-state since 1923 and licensed in Indiana, Kentucky, and Illinois. Our team of insurance specialists has more than 1,000 years of combined experience helping businesses sort out coverage, and we’ll walk you through the details so you understand what you’re buying.
For most businesses, we typically recommend a starting point of $1,000,000 in liability coverage, then adjust from there as you add vehicles, hire drivers, or open new locations.
Frequently Asked Questions About Commercial Auto Insurance
Will my personal auto policy cover a work-related accident?
Usually not. Personal auto policies commonly exclude business use, so a claim from a work-related accident can be denied. If you regularly drive for work, you need a commercial auto policy, or at least hired and non-owned coverage for vehicles you don’t own.
What is the difference between hired and non-owned auto coverage?
Hired auto covers vehicles your business rents, leases, or borrows. Non-owned auto covers employees’ personal vehicles used for work. HNO combines both in one endorsement, and it’s liability-only, so it doesn’t cover physical damage to the vehicle or the driver’s injuries.
How much does commercial auto insurance cost?
There’s no flat rate. Cost depends on your vehicles, how you use them, your drivers’ records, your location, and your limits, and premiums have been rising industry-wide. The most accurate way to find out is to have an agent quote your specific situation across carriers.
Is commercial auto insurance tax deductible?
Premiums for vehicles used for business are generally deductible as a business expense, but every situation is different. Ask your tax advisor how it applies to your business.
Do I need commercial auto if my business doesn’t own any vehicles?
Possibly, yes. If employees drive their own cars or rent vehicles for work, hired and non-owned auto coverage fills the gap your commercial and personal policies leave open. It’s a common blind spot for businesses that assume no company vehicles means no auto exposure.
Get Commercial Auto Coverage That Fits How You Work
Every business uses vehicles a little differently, and the right mix of commercial auto and HNO coverage depends on yours. If you’re not sure what your current policy covers, the team at Torian Insurance can review your situation and help you find commercial auto insurance coverage that fits how you actually work.